Maleic anhydride occupies a unique position in the chemical industry because it connects basic petrochemical feedstocks with a wide range of high-value specialty polymers and performance materials. Although produced in significantly smaller volumes than commodity chemicals such as ethylene or propylene, maleic anhydride is an essential intermediate for industries including construction, composites, coatings, automotive manufacturing, renewable energy, food ingredients, and specialty chemicals. Procurement professionals often encounter products such as unsaturated polyester resins, alkyd coatings, fumaric acid, or malic acid without realising that many of these value chains begin with maleic anhydride. Understanding its production routes and downstream applications provides valuable insight into how upstream feedstock economics influence the cost and availability of numerous specialty materials used across modern manufacturing.
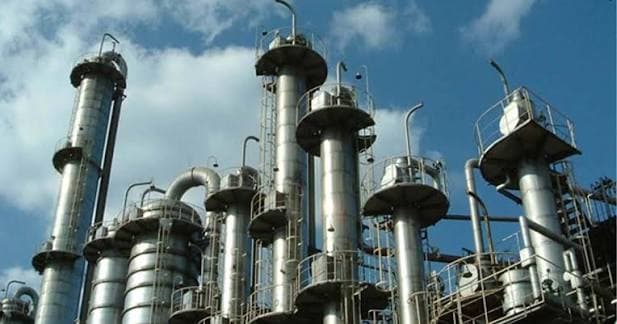
Commercial maleic anhydride is manufactured through the catalytic oxidation of hydrocarbon feedstocks. Historically, Benzene served as the principal raw material, but advances in catalyst technology and changing feedstock economics have led many producers to adopt Butane as the preferred feedstock for new production facilities. During either process, the hydrocarbon is oxidised in the presence of a catalyst to produce maleic anhydride, which is then purified for downstream chemical manufacturing. The choice between benzene and butane significantly influences production economics because the two feedstocks differ in cost, availability, environmental performance, and process efficiency. Regions with abundant and competitively priced butane often favour the butane route, while existing infrastructure or regional feedstock availability may support continued benzene-based production in certain locations. As a result, fluctuations in either aromatic or natural gas liquid markets can influence maleic anhydride production costs depending on the technology employed by individual manufacturers. Procurement professionals evaluating suppliers should therefore understand not only product specifications but also the production route supporting those specifications, as feedstock selection can affect long-term competitiveness and market resilience.
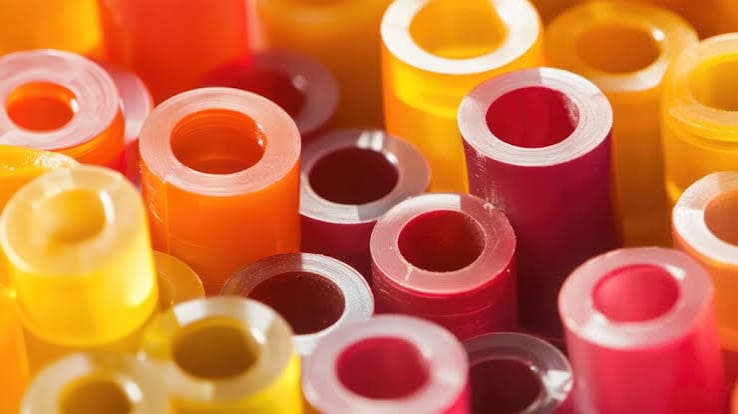
The largest downstream application for maleic anhydride is the production of unsaturated polyester resins (UPR), one of the world's most important thermosetting polymer systems. These resins are widely used in boat hulls, building panels, sanitary ware, storage tanks, pipes, automotive components, and increasingly in wind turbine blades, where high strength, corrosion resistance, and relatively low weight make composite materials particularly attractive. Because construction activity, infrastructure investment, and renewable energy projects consume substantial quantities of unsaturated polyester resins, these sectors have become the principal demand drivers for maleic anhydride. Growth in wind power installation has added another important source of long-term demand, as composite blade manufacturing relies heavily on polyester resin systems. Beyond composites, maleic anhydride is also used in the production of alkyd resins for industrial coatings, Fumaric acid, Malic acid, lubricant additives, agricultural chemicals, paper treatment agents, and a variety of specialty copolymers that improve material performance in packaging, engineering plastics, and industrial applications. This broad derivative portfolio makes maleic anhydride one of the most versatile intermediate chemicals in the specialty polymer industry.
For procurement professionals, understanding the maleic anhydride value chain provides a stronger framework for evaluating market developments and supplier strategies. Demand growth is influenced not only by traditional construction markets but also by structural trends such as renewable energy expansion, lightweight composite adoption, and infrastructure investment. At the same time, feedstock economics remain an important consideration because benzene- and butane-based production routes respond differently to changes in crude oil, natural gas liquids, and petrochemical markets. Supplier competitiveness may therefore vary according to regional feedstock advantages, production technology, and downstream integration. Procurement teams sourcing polyester resins, specialty coatings, composite materials, or derivative chemicals should monitor both construction activity and upstream feedstock markets when assessing future pricing and supply conditions. Maleic anhydride demonstrates how a relatively small-volume intermediate can exert significant influence across multiple industrial sectors by linking petrochemical feedstocks with advanced polymer technologies. Buyers who understand this connection are better equipped to interpret market signals, evaluate supplier capabilities, and build sourcing strategies that reflect both upstream production economics and downstream demand fundamentals.
Looking for specialty polymer procurement intelligence or maleic anhydride market insights? Understanding feedstock routes, downstream applications, and construction-driven demand helps buyers interpret market trends and strengthen sourcing decisions across composites, coatings, and specialty chemicals.
Maltodextrin (E1400) CAS: 9050-36-6